It's pouring rain, there's a weird drip sound coming from the hallway ceiling, and you're standing there in your socks thinking "well, that's what insurance is for, right?" Kind of. Sometimes. It depends on about six different factors that most people never think about until they're filling out a claim form at 9pm with a bucket catching water two rooms away.
Roof damage and home insurance is one of those areas where the fine print does a lot of heavy lifting, and getting it wrong can mean a denied claim right when you need the payout most. So let's go through what actually gets covered, what usually doesn't, and how to stack the odds in your favour before disaster strikes.
Sudden and accidental usually gets the green light
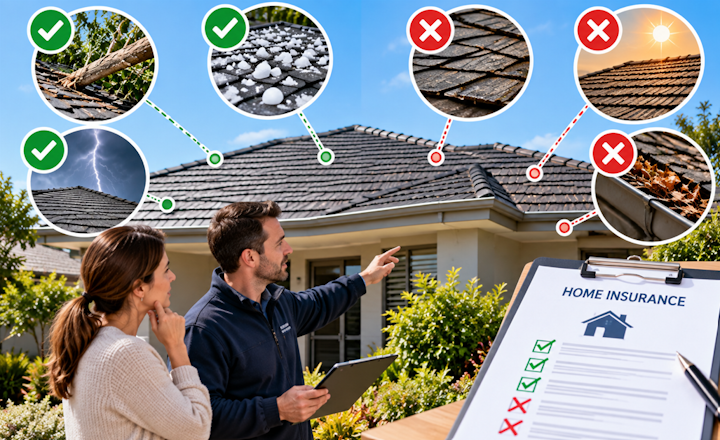
Insurers generally cover damage that happens suddenly and outside your control. Think storms, hailstorms (very much a Sydney speciality some years), a tree branch coming down in high wind, or a one off event like a falling object. These claims tend to move relatively smoothly because the cause is obvious and undeniable. A photo of a snapped branch sitting on cracked tiles pretty much tells the whole story on its own.
Wear and tear is where things get messy
Here's the part that catches people off guard. If your roof has been slowly deteriorating over years, cracked tiles from age, rusted flashing, a slow leak that's been dripping quietly for months, insurers will almost always classify that as wear and tear or lack of maintenance, not an insurable event. Wear and tear is specifically excluded in nearly every standard home insurance policy in Australia. The logic insurers use is simple: maintenance is the homeowner's job, not theirs.
This is honestly one of the biggest reasons homeowners get frustrated with claims. They assume "the roof failed" automatically means "insurance pays," but assessors are trained to spot the difference between a sudden event and a slow, ongoing problem. If they see moss buildup, degraded sealant, or tiles that look like they've been cracked for a long time rather than freshly damaged, that's often enough to knock a claim back entirely.
Keeping your roof in good shape protects your claim, not just your roof
This is where regular restoration and maintenance work double duty. A well maintained roof is less likely to fail in the first place, but it also gives you a paper trail. If an assessor can see invoices showing the roof was professionally restored, inspected, or repaired within the last few years, it strengthens your case that the damage in question was sudden rather than neglected.
What the claims process actually looks like
When damage happens, most insurers want photos taken as soon as it's safe, a description of what caused it (storm date, wind event, whatever the trigger was), and in many cases a professional assessment from a roofer or builder. This is where hiring someone who's done insurance work before really pays off, because they know exactly what an assessor needs to see in a report: clear photos, cause of damage stated plainly, and an itemised repair estimate.
Don't wait weeks to report damage either. Insurers can and do question delayed claims, wondering why nobody flagged the leak sooner. If you notice something, even a small stain on the ceiling, get it looked at and documented straight away.
Common reasons claims get denied
A few patterns show up again and again. Claims get denied when the damage is deemed gradual rather than sudden, when there's evidence of poor maintenance such as blocked gutters causing water to back up, when the roof was already flagged as needing repair in a previous inspection and nothing was done about it, or when the paperwork submitted is vague about cause and timing. None of these are things insurers invented to be difficult, they're written into most standard policies, so reading your actual policy document rather than just the marketing brochure is worth the twenty minutes it takes.
A simple habit that saves a lot of grief later
Get your roof looked at once or twice a year, ideally before and after the wetter months. A quick seasonal check catches small issues, a lifted tile, a cracked seal around a vent, before they become the kind of slow leak that gets your claim rejected as wear and tear.
A full seasonal roof maintenance checklist that covers exactly what to look for each season, handy if you'd rather handle some of it yourself between professional inspections.
What to do the moment you spot damage
Step one, make sure it's safe, don't go climbing onto a wet roof after a storm. Step two, photograph everything visible from the ground or from inside, including any ceiling stains or pooling water. Step three, call your insurer to start the claim and ask exactly what documentation they want. Step four, get a roofer out for a proper assessment, ideally someone who's dealt with insurance claims before and knows how to write a report that actually holds up.
Actual cash value versus replacement cost, know which one you signed up for
Not all policies pay out the same way. Some cover the actual cash value of your roof, meaning they factor in age and depreciation, so a twenty year old roof might only get you a fraction of what a brand new one costs to install. Others cover full replacement cost regardless of age. This distinction rarely gets explained clearly when people first sign up for a policy, and it's one of those details that only becomes obvious the day you're staring at a settlement offer that's way less than you expected. It's worth calling your insurer once a year just to confirm which type of cover you actually have, rather than assuming.
Flood, storm, and the grey area in between
Here's a distinction that trips a lot of people up. Storm damage, wind ripping tiles off, hail cracking a skylight, is usually covered under standard building insurance. Flood damage, water entering from rising rivers, stormwater drains overflowing, or general flooding events, often sits under a separate flood cover component that not every policy includes by default. If heavy rain causes water to pool on your roof and eventually seep in because of a blocked gutter rather than wind damage, insurers might argue that's a maintenance issue rather than a flood or storm event. The line between these categories genuinely comes down to specific wording, so if you live somewhere prone to heavy rain events, it's worth asking your insurer directly how they define each category rather than guessing.
The bottom line
Insurance is there for the storm that catches you off guard, not the roof that's been quietly falling apart for five years. The good news is that staying on top of basic maintenance does double duty, it keeps your roof functional and it keeps your claim legitimate if something genuinely does go wrong. A bit of record keeping and a couple of inspections a year is a small price to pay compared to the headache of a denied claim after a real storm.
| < Prev | Next > |
|---|